01 · Hong Kong LPF Registration, Acquisition and Transfer
Prepared by Rengangyongsheng (Hong Kong) Limited, with professional explanation by Drew Tang, Business Manager.
 RengangyongshengRENGANGYONGSHENG · HONG KONGBook a consultation
Bring registration, role responsibilities and transaction closing together in one clear report.
12-page professional presentation · 2026-10-21 · Official information prevails
Verbatim script and presentation outline Client-specific PPT and full verbatim script Winding-up and Exit PPT and Complete Verbatim ScriptThe PPTs, PDFs, image previews and original downloads on this page are in Simplified Chinese. The Traditional Chinese and English pages provide corresponding text descriptions and complete online presentation scripts.
The PowerPoint version is editable; the PDF is convenient for viewing across browsers. The files are for general informational presentations only and do not constitute regulatory approval or investment advice.
Prepared specifically for project decisions and client briefings, the 12 pages cover application documents, fees, the four roles, transaction counterparties, due diligence, closing, LPF and OFC, and tax conditions. The original role and process briefing materials remain below on this page.
Prepared by Rengangyongsheng (Hong Kong) Limited · Professional explanation by Drew Tang, Business Manager · 2026-10-21
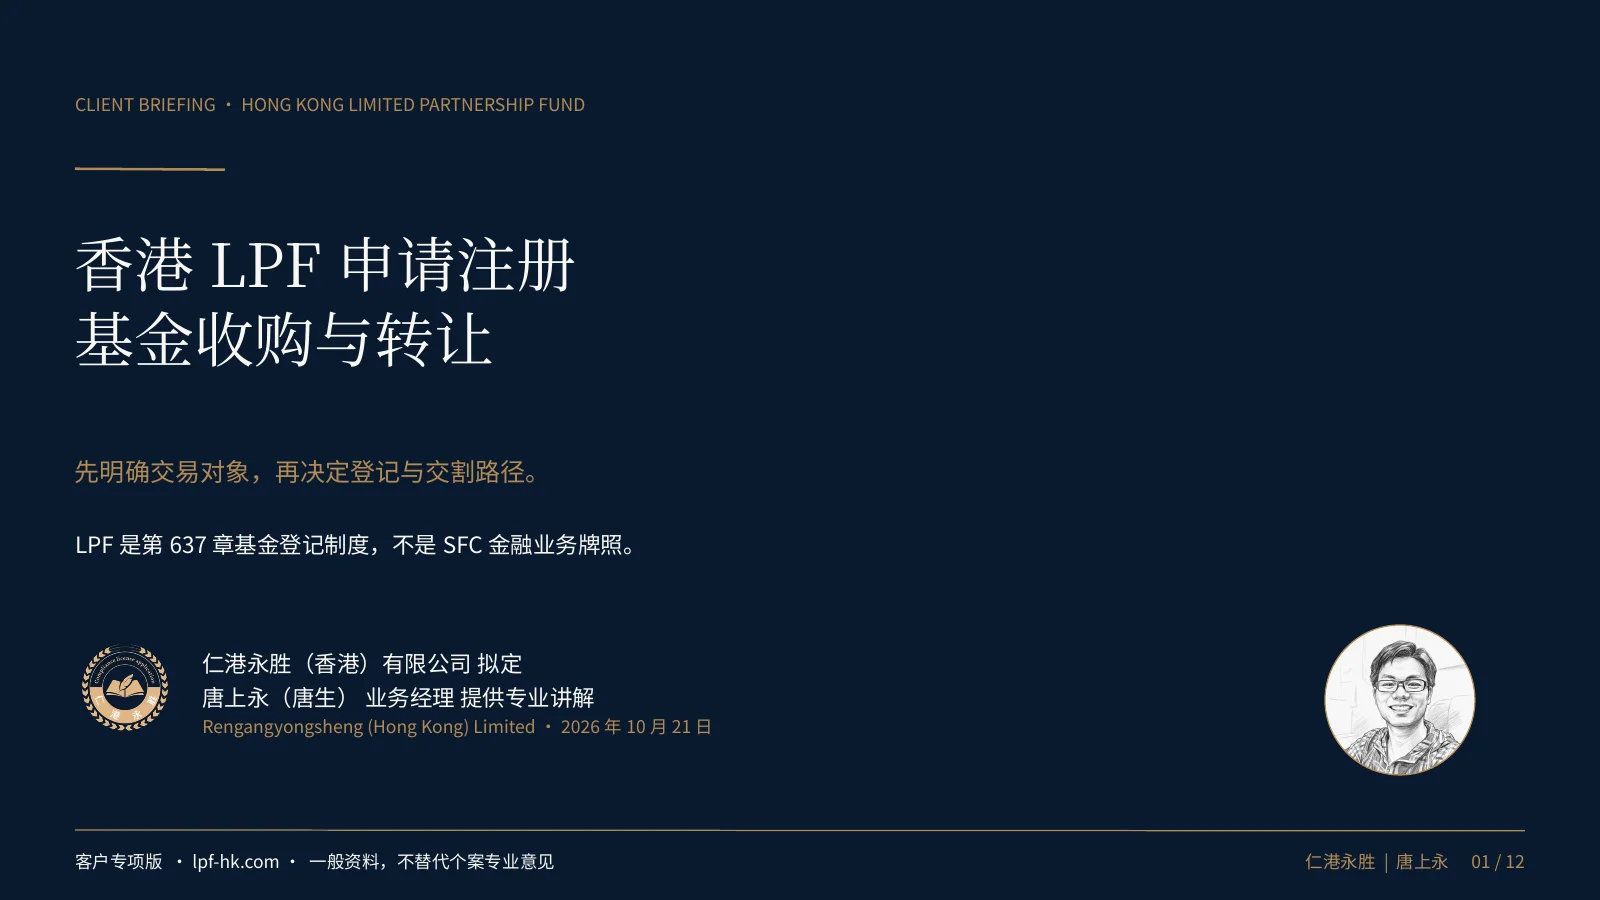
Review the key points page by page in the latest 12-page client-specific PPT, then read the full verbatim presentation transcript below. A presentation of approximately 20–27 minutes is recommended; rehearse to check timing for live delivery speed, pauses and questions and answers.
Key points:An LPF is a registered fund vehicle, not an SFC licence. First distinguish registration, licensing, tax and transaction pathways, then discuss the outcome the client seeks.
Presentation transition:Establish the correct positioning of an LPF; next, define the client's intended outcome before comparing new establishment with different acquisition routes.
Read the full verbatim transcript for this pageKey points:The choice of route depends on what the client seeks to acquire and the commercial outcome, not merely on which route appears faster.
Presentation transition:Clarify the transaction objectives using six facts; then distinguish the four LPF roles and assess the relevant licensing requirements.
Read the full verbatim transcript for this pageKey points:GP, LP, IM and RP have distinct responsibilities; the RP must not be confused with the AR in certain structures, and licensing for investment activities must be assessed on the facts.
Presentation transition:Clarify roles and boundaries of responsibility; next, move on to the documents, forms and registration steps for establishing a new LPF.
Read the full verbatim transcript for this pageKey points:The establishment process should be driven by the project's facts and documentation arrangements. The appropriate forms and submission method must be checked against the applicable circumstances.
Presentation transition:Show clients that registration is not a single form, but a set of ongoing arrangements; the next page distinguishes three categories of fees: application, business registration and annual returns.
Read the full verbatim transcript for this pageKey points:CR application fees, business registration fees and ongoing filing fees are separate items; although the LPA is not submitted to CR, it remains a core transaction and governance document.
Presentation transition:Establish the budget and review priorities through clear fees and document scope; next, focus on three different transaction targets.
Read the full verbatim transcript for this pageKey points:A transfer of LP interests, an equity transaction in the GP entity and replacement of the GP at LPF level are three different transactions; none automatically substitutes for another.
Presentation transition:First define precisely what is being bought and sold; if considering an acquisition, the next step is to verify through due diligence what will be acquired and which liabilities will be assumed.
Read the full verbatim transcript for this pageKey points:Due diligence should organise evidence around acquisition of the target, assumption of liabilities and completion conditions, rather than stop at a document checklist.
Presentation transition:Turn risk findings into actionable conditions; the next page coordinates agreements, conditions precedent, closing checks and CR notifications.
Read the full verbatim transcript for this pageKey points:Transaction closing requires coordinated management of agreements, conditions, closing checklists and notices; a sale and purchase agreement alone is not sufficient.
Presentation transition:Ensure continuity of responsibilities, assets and notices; then compare LPF and OFC, returning to which vehicle better fits the commercial arrangements.
Read the full verbatim transcript for this pageKey points:LPFs and OFCs differ in legal form, governance and registration routes. The choice should be determined by commercial arrangements, not promotional labels.
Presentation transition:Choose the vehicle based on governance and commercial needs, not labels; then discuss tax conditions, evidence and limits of applicability separately.
Read the full verbatim transcript for this pageKey points:Verify UFE, carried interest and stamp duty separately; LPF registration does not confer automatic tax exemption, and the status of tax amendments must be confirmed as at the verification date.
Presentation transition:Do not treat structure registration or reform proposals as tax conclusions. Next, ask the client to provide facts and documents to develop a verifiable proposal.
Read the full verbatim transcript for this pageKey points:First collect the facts of the client’s project and existing documents, then deliver pathway, risk and closing work products in stages.
Presentation transition:Explain how client information is translated into phased deliverables; conclude the discussion with 3 action steps and a review before formal implementation.
Read the full verbatim transcript for this pageKey points:Select a route based on a fact-finding interview, and review the then-current official CR, SFC and IRD materials before submission or closing.
Presentation transition:After completing the fact-finding interview and selecting a route, the relevant professionals should confirm and implement it based on the facts; this page concludes the presentation with thanks and contact methods.
Read the full verbatim transcript for this pageThe full script takes approximately 20–27 minutes; a timed rehearsal is required to confirm the actual duration. The PPT also includes concise speaker notes for each slide; the text below and the downloadable file contain the full spoken script.
An LPF is a fund registration regime, not an SFC licence. Legal, tax, fundraising and transaction implementation matters require separate review based on the facts; registration, tax exemption, licensing, account opening and closing outcomes are not guaranteed.
12 pages cover route selection, assets and liabilities, creditors, LPF7 and LPF8, GP and SFC status, tax, records and cross-border repatriation. Winding up, dissolution and deregistration are not the same action.
Prepared by Rengangyongsheng (Hong Kong) Limited · Professional explanation by Drew Tang, Business Manager · 2026-10-21
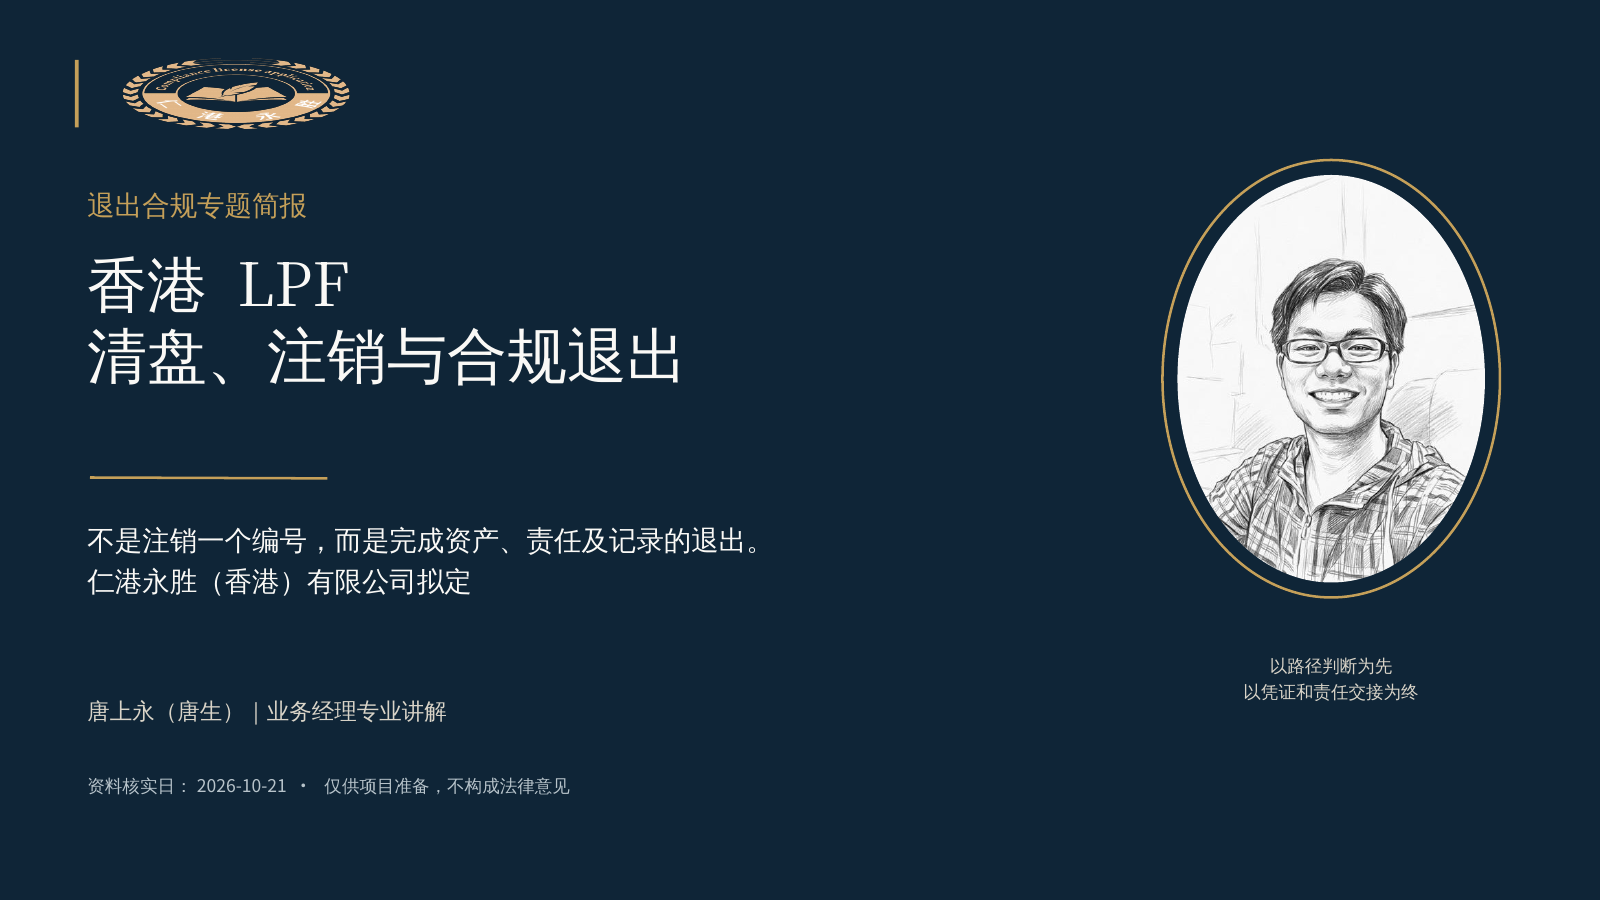
Read the complete text in twelve-slide order. Allow approximately 16–22 minutes, including pauses and slide changes; confirm timing by rehearsal. The PowerPoint includes corresponding speaker notes.
Deregistering an LPF does not extinguish liabilities. Forms, deadlines, fees and settlement arrangements must be reviewed against the actual route, the LPA and applicable legislation; this presentation is not a substitute for case-specific legal, tax or banking advice.
Prepared by Rengangyongsheng (Hong Kong) Limited, with professional explanation by Drew Tang, Business Manager.
An LPF is a fund registration regime administered by the Companies Registry, not a financial business licence, and has no separate legal personality. SFC, business registration and tax requirements are assessed separately.
GP management and ultimate responsibility, LP contributions, IM day-to-day investment management, and RP anti-money laundering measures; the requirement for an authorized representative is assessed separately according to the GP category.
Clarify management control, proper custody and governance arrangements; appointing service providers does not automatically transfer the GP’s statutory responsibilities.
Assess contributions and transfers under the LPA; day-to-day management may affect liability. Check the Schedule 2 safe harbours and professional investor rules separately.
Assess Type 9 requirements based on actual management activities, locations and the delegation chain; a GP holding concurrent roles and outsourcing are not unconditionally exempt from licensing.
Verify the qualifications of authorised institutions, licensed corporations, accounting or legal professionals, and implement CDD, beneficial owner identification, monitoring and records handover.
Assessment, roles, agreements, documents, submission by a Hong Kong solicitor, certificates, account opening and operational handover. LPF1 is accompanied by IRBR4; the LPA need not be submitted to CR.
CR registration application HK$3,034, 2026/27 1-year business registration HK$2,350, standard LPF5 filing HK$105; usual processing times are not guaranteed.
A transfer of LP interests, a sale of equity in the GP entity and replacement of the statutory GP are three different events; an LPF must not be treated as a financial licence transfer.
Review the LPA, assets, liabilities, tax, AML and historical liabilities; secure consents, bank signing arrangements and applicable CR change notifications.
First confirm the business strategy, personnel and capital, then decide on the registration or transaction pathway. Consult official materials and book a specialist consultation with Drew Tang.
Closely aligned with the existing 12-page presentation, this provides a complete verbatim script for reading aloud and a presentation outline. Each page includes key points, spoken text and a transition to the next page, for internal presentations, client discussions or pre-meeting preparation.
Rengangyongsheng (Hong Kong) Limited | Drew Tang, Business Manager. Estimated25.1minutes; actual duration requires a trial reading and allowance for pauses and questions.
Download speech verbatim scriptPresentation objectives, key points, transitions and suggested Q&A are organised in 12-page order. The Markdown file can be viewed directly in a text editor or an application supporting Markdown.
Download presentation outlineNo. An LPF is a fund vehicle registered with the Companies Registry. Investment management, dealing, marketing and other activities require separate analysis under the SFO and SFC licensing requirements based on the actual personnel, locations, authority and Hong Kong connections. Type 9 cannot be obtained automatically through LPF registration either.
Not necessarily. A change in the equity ownership of the GP entity and the statutory withdrawal, removal or replacement of the GP at LPF level are separate matters. Changes of control, the LPA, investor consent, banking and contractual succession arrangements, and applicable CR notifications must be checked separately; historical liabilities do not automatically disappear either.
The CR FAQ does not list a requirement that every LP be a professional investor or a uniform minimum contribution as a general condition for LPF registration. The offering method, target investors, strategy, documents and applicability of the SFO must still be verified against the specific facts; registration conditions must not be treated as fundraising rules.
Roles may be combined where the relevant eligibility requirements are met, but combining roles does not change their boundaries. A GP also acting as IM must still assess Type 9 and other regulated activities; a GP also acting as RP must still implement CDD, beneficial owner identification, ongoing monitoring, escalation and record retention.
No. Section 29 of Cap 637 requires LPF transaction documents and records to be retained for at least seven years. Schedule Two to the AMLO sets out separate statutory rules for when retention periods for CDD and transaction records begin. Confirm these separately according to record category, the end of the business relationship or transaction, and current legislation.
The presentation script provides a general business overview and does not constitute legal, tax or investment advice; for in-depth tax analysis and the latest conditions, please refer toRegistration Guide: Tax Topics. Numbers in square brackets identify sources for reference and need not be read aloud during the presentation; the downloadable script matches the online text.
LPF registration is not a securities or asset management licence; fees, filing deadlines and role eligibility must be confirmed against the official rules at the time of application and the circumstances of each case. Transfers and acquisitions are subject to the partnership agreement, parties' consent, and regulatory and tax conditions.
Book a specialist consultation with Drew Tang